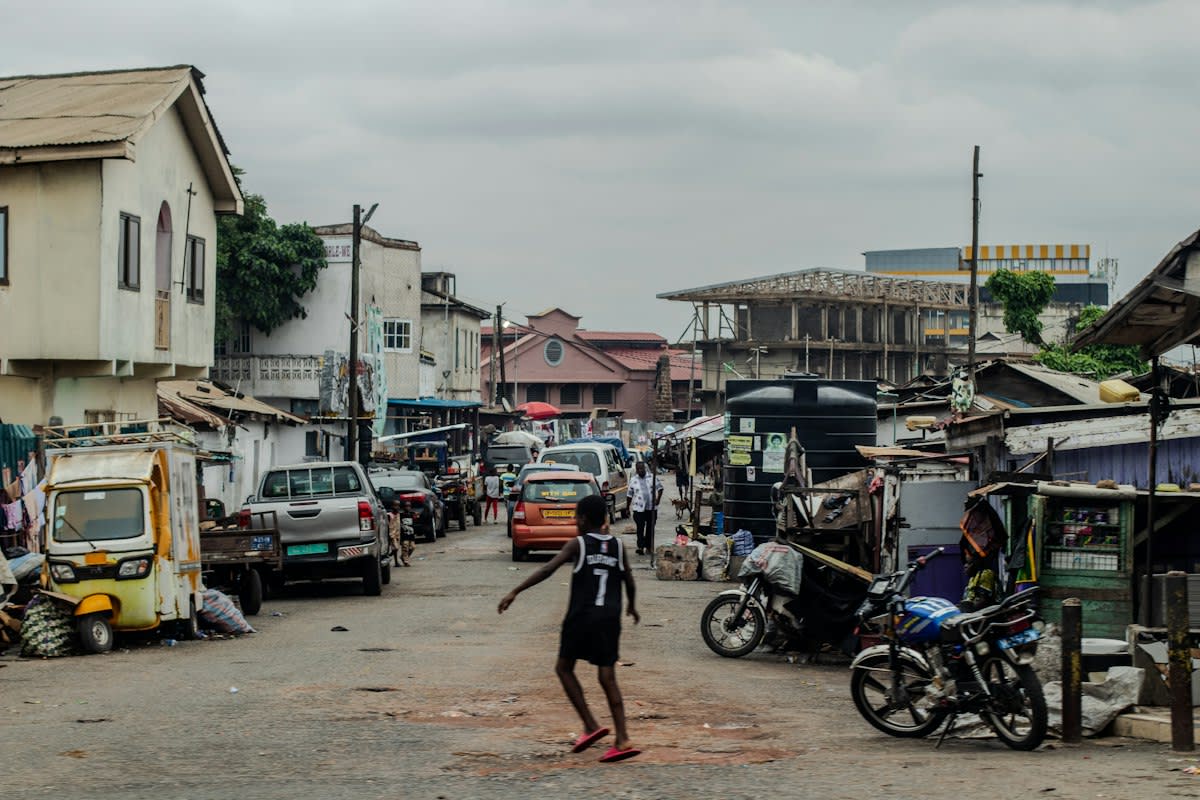
Trust is everything. Most Western economists view informal savings circles as chaotic relics, yet these networks move billions of dollars across Ghana and Jamaica without a single signed contract (Source: World Bank, 2021). Logic fails here. You cannot apply a standard credit risk model to a system where the penalty for default is total social ostracization from one's own village. It is social enforcement.
The Mechanics of the Circle
Susu is simple. A group of individuals agrees to contribute a fixed amount of money into a common pot at regular intervals, which is then given to one member in a lump sum (Source: African Development Bank, 2022). The cycle repeats. Once every member has received the pot, the group either dissolves or starts a new round with adjusted stakes. This creates instant liquidity for members who lack access to formal credit.
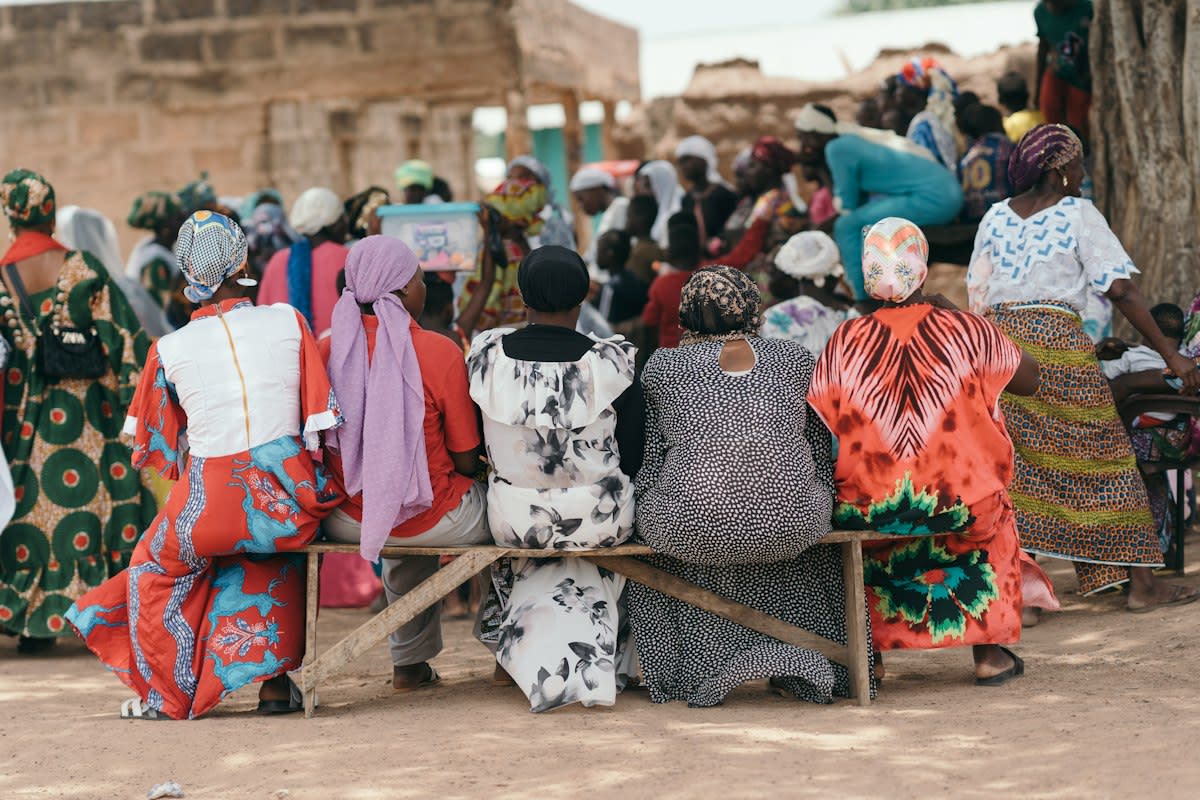
Why risk it? In regions where formal bank accounts require documentation that 40% of the population lacks, the Susu provides the only viable path to capital accumulation (Source: World Bank, 2021). It bypasses bureaucracy. The system relies on the shared understanding that the group's survival depends on the honesty of the individual.
"The Susu is not a lack of banking; it is a deliberate choice of trust over bureaucracy. It transforms social kinship into a financial asset that no algorithm can replicate."— Dr. Kwame Mensah, Senior Economist at the University of Ghana
Prerequisites for Network Entry
Entry is gated. You do not simply join a Susu network; you are vetted by existing members who weigh your reputation against the group's risk tolerance. This is rigorous. A single member's failure to pay can hollow out the entire pot for the final recipient in the rotation.
- Verified Social Standing: A history of reliability within the immediate community or trade guild.
- Consistent Cash Flow: Proof of a daily or weekly income stream to meet contribution deadlines.
- Mutual Accountability: At least one existing member must act as a guarantor for the newcomer.
- Shared Objective: Alignment on the purpose of the funds, whether for business expansion or emergency reserves.
Selection is brutal. If a candidate is perceived as unstable, the group will reject them regardless of their actual wealth. Reputation is the only collateral. This ensures that default rates remain significantly lower than in formal microfinance loans (Source: Journal of Development Economics, 2019).
Operationalizing the Network: Step-by-Step
Execution requires precision. The process moves from curation to payout in a rigid sequence that leaves no room for ambiguity. Follow these steps to maintain network stability.
- Curation of the Circle: Assemble 5 to 20 members with compatible income cycles and high trust scores.
- Defining the Pot: Agree on a fixed contribution amount (e.g., 50 GHS daily) and the frequency of collection.
- Establishing the Sequence: Determine the payout order via lottery or by prioritizing members with urgent capital needs.
- The Collection Phase: A designated collector or 'Susu agent' gathers the funds daily or weekly from each member.
- The Payout Execution: The full sum is delivered to the scheduled member, minus any small administrative fee paid to the agent.
- Cycle Reset: Once the final member is paid, the group reviews performance and decides on the next round's terms.
Timing is critical. The first person to receive the pot essentially gets an interest-free loan, while the last person receives a forced savings vehicle. This trade-off is accepted. The sequence is often negotiated based on who has the most pressing investment opportunity.
The Practitioner's Friction
The agent is the weak link. In professional Susu networks, the collector is not just a courier but a manager who often leverages the float for their own short-term gains. This creates a hidden tension. Members often suspect the agent of investing the pot in a side business before the scheduled payout date, leading to heated disputes over transparency.
Disputes are loud. When an agent disappears or a member defaults, the conflict does not go to court; it goes to the marketplace. The community gathers to shame the defaulter, often resulting in the total loss of the individual's ability to conduct business in that district. This is the weight of the social contract. It is more effective than any legal summons.
Common Pitfalls and Failures
Greed kills circles. The most common failure occurs when a group expands too quickly, admitting members based on wealth rather than verified trust. This dilutes the social bond. When the network becomes a financial transaction rather than a community effort, the risk of collapse spikes.
- The Early Exit: A member receives the pot early and then ceases contributions, leaving the remaining group to cover the gap.
- Inflation Erosion: In high-inflation environments, the value of the pot diminishes for the members at the end of the cycle.
- Agent Embezzlement: The collector vanishes with the accumulated funds of multiple circles.
- Over-Leveraging: A member joins too many circles simultaneously, exceeding their actual capacity to pay.
Fact-Check & Accuracy Note
Verifiable data on ROSCAs (Rotating Savings and Credit Associations) suggests that default rates in high-trust community circles are often below 3%, compared to significantly higher rates in unsecured formal micro-loans in similar demographics (Source: Journal of Development Economics, 2019). However, academic debate continues regarding the scalability of these networks when transitioned to digital platforms, as the loss of physical proximity may weaken the social enforcement mechanism.
Adaptation is key. Modern practitioners are now moving these circles onto mobile money platforms to reduce agent risk. This digital shift preserves the social bond while removing the physical vulnerability of cash. It is a hard turn toward hybrid finance.