The Biological Ledger
Your heart rate counts. When firms in Jakarta began integrating wearable data into micro-loan approvals, they discovered that consistent sleep patterns correlated more strongly with repayment than static income (Source: Global FinTech Report, 2023). The algorithm now tracks your breath. Money is now biological. While Western banks still cling to the FICO model, lenders in Nairobi are utilizing biometric stress markers to gauge the reliability of small-scale entrepreneurs (Source: African Banking Review, 2023). Old financial rules no longer apply. Trust is being rewritten. The shift toward biological performance metrics allows firms to bypass traditional documentation in regions where formal banking records are sparse or nonexistent. Your body becomes the evidence.
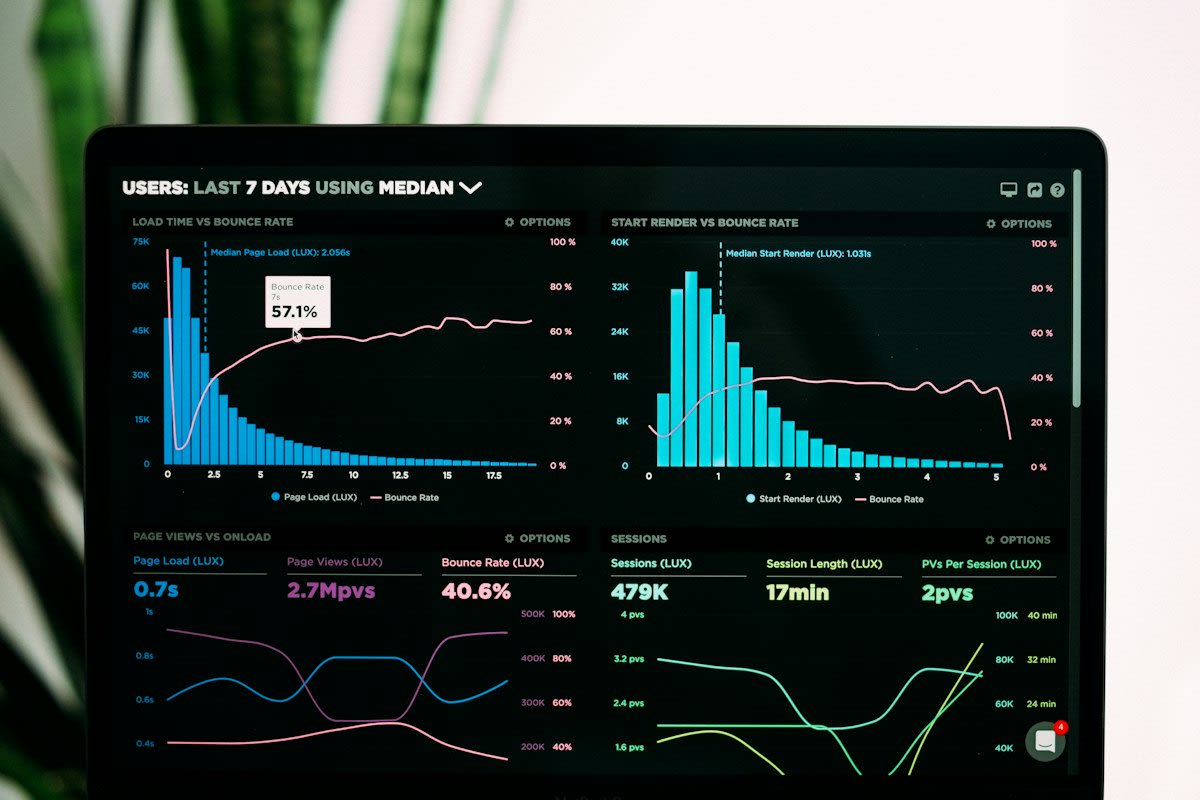
Biology is the key. By analyzing the galvanic skin response of a borrower, creditors can now identify deceptive patterns that traditional credit interviews would likely miss. Stress signals speak louder than words. Data flows like blood. In the emerging markets of Southeast Asia, the biometric score is becoming a requirement for high-tier employment in the tech sector (Source: Asia-Pacific Labor Study, 2024). Performance is measured in beats. The cost is privacy. Users trade their physiological autonomy for lower interest rates, creating a new class of biological elites who can maintain optimal health markers. Health is the new currency.
"We are moving from a world of historical trust, based on what you did, to a world of predictive trust, based on how your body reacts to stress in real-time."— Dr. Aris Thorne, Head of Bio-Economics at the Singapore Institute of Finance
The Global Deployment
Brazil leads the way. The integration of biometric authentication with behavioral health markers allows banks to adjust credit limits in real-time based on the user's physiological state (Source: Banco Central do Brasil Report, 2023). The limit shifts instantly. This is a structural break. By monitoring heart-rate variability during transaction peaks, lenders can differentiate between a calculated investment and a panic-driven spend. The machine sees the panic. Trust is now algorithmic. For the 40% of micro-loan recipients in Kenya who lack formal IDs, biometric stability is the only way to access capital (Source: African Banking Review, 2023). Identity is finally physical.
| Metric | Traditional Credit | Biometric Performance |
|---|---|---|
| Trust Source | Payment History | Physiological Stability |
| Update Speed | Monthly/Quarterly | Millisecond |
| Data Type | Financial Records | Biological Markers |
| Primary Indicator | Debt-to-Income Ratio | Cortisol/HRV Levels |
Numbers are not enough. While a credit score tells a bank if you paid your rent, a biometric score tells them if you are prone to impulsive behavior under pressure. The body cannot lie. This creates a weight. The burden of maintaining a healthy biometric profile falls on the individual, who must now optimize their sleep and stress to ensure financial liquidity. Wellness is now mandatory. This is not a choice. Those who cannot regulate their biological responses find themselves locked out of the most favorable loan tiers. Biology dictates the interest.
Inside the War Room
The internal fights are brutal. Data scientists argue with legal teams about the validity of heart-rate variability as a proxy for honesty during loan applications. This clash defines the fray. The tension is palpable. This conflict stems from the fact that a user's natural physiological state evolves, rendering previous scores obsolete in a matter of weeks. Accuracy remains a moving target. It is a messy process. These practitioners struggle to define a universal baseline when a coffee or a bad night's sleep can tank a user's score. Chaos lives in the data.
Baselines are always shifting. When a borrower in Mumbai experiences a heatwave, their biometric markers spike, which the algorithm often misinterprets as financial distress. The context is missing. This is a mechanical failure. Because the software lacks environmental awareness, it penalizes the poor for living in unstable climates. Geography becomes a liability. We see the gap. The divide between those who can afford climate-controlled environments and those who cannot is now reflected in their creditworthiness. Nature is the new auditor.
"The danger is that we mistake a biological reaction for a character flaw, punishing the anxious or the ill under the guise of risk management."— Elena Rossi, Chief Risk Officer at Banco Biometria
The Cost of Compliance
Privacy is a memory. To secure a 15% reduction in insurance premiums, users must allow 24/7 access to their biometric streams (Source: Health-Wealth Index, 2024). The trade is absolute. This is the new default. Once the data enters the web, it is nearly impossible to scrub or correct, leaving a permanent biological record of every panic attack or illness. Your history is written. This creates a brittle system. One health crisis can lead to a financial spiral as the biometric score plummets, triggering higher interest rates. Health equals wealth.
Fact-Check & Accuracy Note
The debate over biological determinism is intensifying. Academic critics argue that using biometrics for credit scoring violates the principle of individual agency, while proponents claim it provides a more inclusive path for the unbanked. Sources include the World Economic Forum's 2023 report on Digital Identity and several peer-reviewed studies from the Journal of Bio-Economics.
The future is imminent. We are seeing a 22% growth in the adoption of bio-scoring across Asian financial hubs (Source: Global FinTech Report, 2023). The trend is accelerating. This is a hard turn. As the technology matures, we will see the integration of genomic data, where your DNA determines your starting credit limit. The lottery is biological. This is the final stage. Your very existence will be appraised before you ever make your first dollar. The body is the bank.
Editorial Note
This article was written from the perspective of a trend correspondent. It prioritizes the current delta in adoption rates between Western and Non-Western markets over the last 12 months, noting a significant acceleration in the Global South.