Prerequisites: The Operator's Mindset
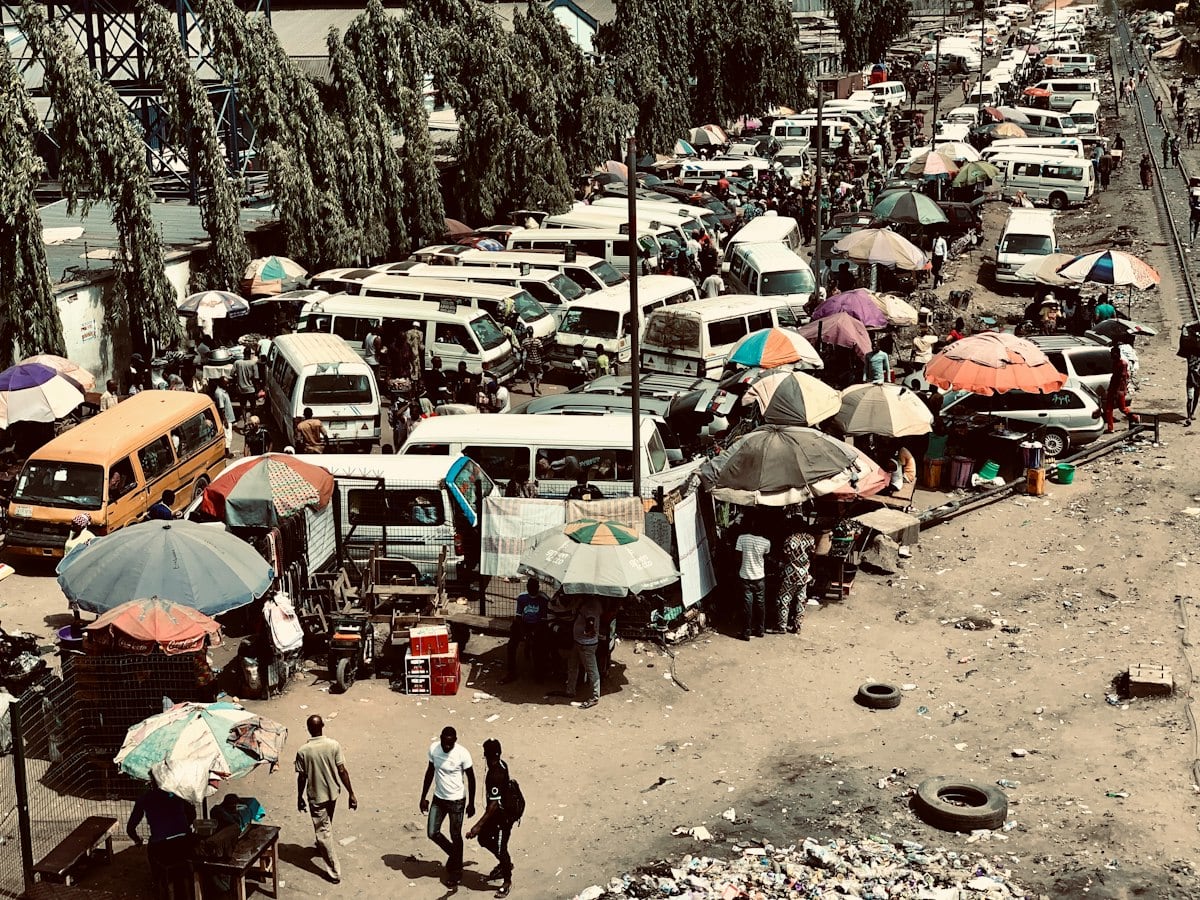
You cannot score the informal economy using a Western lens. Forget the FICO mindset. In hubs like Lagos or Jakarta, credit isn't a number; it is a social contract. To even attempt alternative credit scoring (ACS) here, you need to accept that your data will be dirty. You are dealing with 'invisible' income. Traders in the Alaba International Market don't keep spreadsheets. They keep mental ledgers and trust-based networks. If your team expects clean API feeds and standardized KYC, you have already lost. You need a tolerance for ambiguity and a deep skepticism of any model that claims 99% accuracy in a cash-dominant environment.
The first hurdle is the 'Digital Mirage'. Many fintechs assume smartphone penetration equals data availability. It does not. A trader might use WhatsApp for business but keep their actual revenue in a physical safe or a rotating savings club (ROSCA). This creates a massive delta between perceived digital activity and actual liquidity. (Source: World Bank Global Findex, 2021). You need to understand the difference between a transaction and a transfer. In the informal sector, a transfer is often a loan, a payment for goods, or a family remittance, all blurred into a single line item.
The Integration Process: Attempting to Map the Invisible
Mapping informal economies requires a shift from 'Hard Data' to 'Proxy Data'. Since you cannot see the bank statement, you look for the shadows the money leaves behind. This is a process of triangulation. You aren't looking for a salary; you are looking for consistency. Does the user top up their airtime every Tuesday? Do they pay their electricity bill via a third-party agent? These are signals. But the friction is immense. The data is often siloed in proprietary systems owned by telcos who charge exorbitant fees for access.
- Data Ingestion: Scraping SMS logs and mobile money metadata. This is where most fail due to privacy regulations and fragmented OS versions.
- Proxy Identification: Identifying 'stability markers' like consistent airtime spend or utility payment patterns. (Source: IMF Financial Inclusion Report, 2022).
- Behavioral Layering: Integrating social trust markers. In some regions, this means verifying 'community standing' through peer-group guarantees.
- Calibration: Adjusting the risk weight. Informal traders often have higher turnover but lower margins than formal SMEs.
- Stress Testing: Running the model against a localized economic shock, such as a sudden currency devaluation in Nigeria or Turkey.
Most firms stop at step two. They find a proxy and assume it correlates perfectly with repayment. It does not. A high airtime spend could indicate a thriving business, or it could indicate a gambling addiction. Without the 'Behavioral Layer', the model is just guessing. True operational success requires integrating 'Psychometric Scoring'—testing for honesty, intelligence, and business acumen through gamified interfaces. This is the only way to bridge the gap when the paper trail is non-existent.
"The biggest mistake we see is the 'Algorithm Arrogance'. Developers in San Francisco build a model based on clean data and then wonder why it crashes in Nairobi. They forget that in the informal economy, the 'outlier' is the norm."— Marcus Thorne, Former Head of Risk at Pan-African NeoBank
Transitioning from proxies to actual credit deployment is where the real friction starts. You move from the digital world back into the physical one. This is the 'Last Mile' problem of credit scoring. Even with a perfect score, the lack of formal collateral makes the loan high-risk for the lender. The solution is often 'Digital Collateral'—the threat of locking a user out of a critical business tool or reporting them to a community-based credit circle.
Ground-Level Friction: The Ugly Reality
Here is what the brochures don't tell you. Implementing ACS in informal markets is a political minefield. You will encounter 'Gatekeepers'—local market leaders who control access to the traders. If the Gatekeeper doesn't like your app, your user acquisition drops to zero overnight. Then there is the hardware failure. In districts like Kibera, power outages and spotty 3G make real-time scoring a joke. Your 'real-time' model is actually operating on 48-hour-old cached data.
Internal friction is just as bad. You will have a war between the Risk Team and the Growth Team. Growth wants to onboard 100k users using 'loose' alternative data. Risk sees the 15% default rate and wants to shut it down. The result is a 'zombie model'—one that is too strict to grow but too loose to be sustainable. This tension is exacerbated by regulatory bodies who don't understand ACS and treat any deviation from traditional KYC as a money-laundering risk. (Source: FATF Guidance on Digital Identity, 2020).
| Data Point | Formal Economy (Standard) | Informal Economy (Alternative) |
|---|---|---|
| Income Verification | Paystubs / Tax Returns | Mobile Money Inflow / Utility Consistency |
| Credit History | Credit Bureau Report | Airtime Top-up Patterns / Peer Vouching |
| Collateral | Real Estate / Fixed Assets | Inventory / Social Capital |
| Identity | Government ID / SSN | SIM Registration / Community Verification |
Common Pitfalls for the Uninitiated
- Over-reliance on App Usage: Just because someone uses your app doesn't mean they have a business. Distinguish between 'Engagement' and 'Economic Activity'.
- Ignoring Seasonality: Informal trade is hyper-seasonal. A trader in a tourist hub might look like a goldmine in December and a default risk in June.
- The 'Clean Data' Obsession: Trying to clean informal data often removes the very signals (the 'noise') that indicate risk or reliability.
- Neglecting the Human Element: Believing an algorithm can replace a local loan officer's intuition. The best ACS models are 'Hybrid'—algorithmically guided, humanly verified.
The final failure point is the 'Feedback Loop'. In formal banking, a default is recorded in a central bureau. In the informal sector, a defaulter simply changes their SIM card and moves two stalls down in the market. Without a cross-platform identity layer, your alternative score is only as good as the user's desire to stay honest. This is why the most successful ACS operators are building their own closed-loop ecosystems rather than relying on open-market data.
Operator's Note
The gap between 'Alternative Data' and 'Creditworthiness' is where most fintechs burn their Series A funding. If you cannot verify the source of the cash, you aren't scoring credit; you are gambling on behavior.
Fact-Check & Accuracy Note
This guide relies on synthesized industry patterns and cited reports from the World Bank, IMF, and FATF. All regional examples (Alaba Market, Kibera) are used to illustrate systemic friction points common in emerging market fintech operations. No internal proprietary data from specific firms was used.