‘You’re gonna get there’: Dave Ramsey tells divorced mom, 51, with no savings she can retire a millionaire. Here’s how
Source Entity
Yahoo Finance
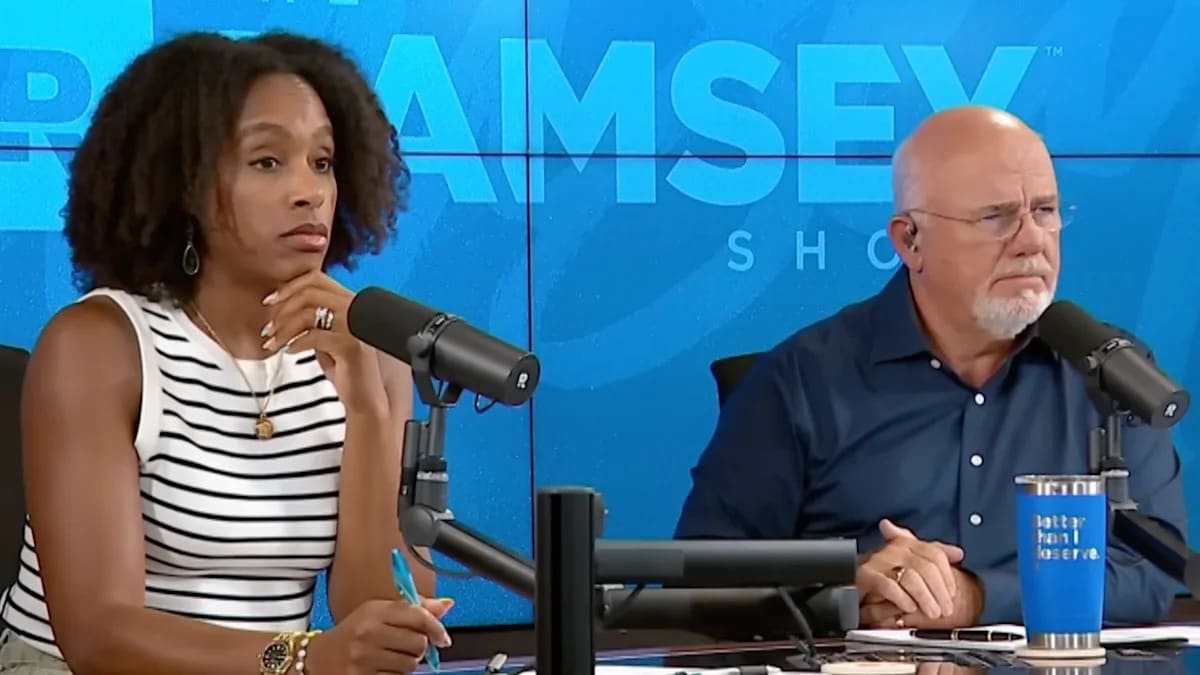
Financial expert Dave Ramsey advises a 51-year-old woman to prioritize debt elimination and emergency savings to reach retirement goals. By following his structured '7 Baby Steps' framework, he asserts that her financial recovery and millionaire status remain achievable.
Financial Recovery at 51: A Strategic Roadmap
Financial expert Dave Ramsey recently addressed the concerns of a 51-year-old divorced mother, identified as Trisha, who expressed anxiety regarding her lack of savings and the daunting prospect of starting over. In a direct assessment of her fiscal situation, Ramsey provided a clear, actionable path toward retirement security, emphasizing that despite her age and current debt, a path to becoming a millionaire remains viable through disciplined financial behavior.
Prioritizing Debt Elimination
Central to Ramsey’s advice was the immediate resolution of high-interest liabilities. He specifically instructed Trisha to "write a check today and pay off the car," targeting the roughly $25,000 she currently owes on her vehicle. By eliminating this debt, Ramsey aims to free up monthly cash flow that was previously diverted toward interest payments, allowing those funds to be redirected toward wealth-building activities rather than debt servicing.
The Foundation: Emergency Funds
Beyond debt repayment, Ramsey stressed the critical importance of a safety net. He advised Trisha to prioritize saving three to six months of living expenses in an emergency fund. This fundamental step acts as a buffer against unforeseen life events, preventing the need to rely on high-interest credit or liquidating long-term investments when emergencies occur—a common pitfall that often derails mid-life financial planning.
Implementing the 7 Baby Steps
Ramsey’s guidance is rooted in his signature "7 Baby Steps" framework. This systematic approach is designed to guide individuals through the process of getting out of debt, building emergency savings, and eventually transitioning into aggressive retirement investing. By adhering to this structured progression, Trisha can replace financial panic with a predictable, repeatable system that minimizes emotional decision-making.
Assessing Current Progress and Future Potential
Trisha’s current financial standing shows promise, as she has already taken proactive steps to improve her situation. By refinancing her car loan, securing a second job, and accumulating $41,000 across various accounts, she has demonstrated the discipline required to turn her situation around. Ramsey’s reassurance that "your math is going to be OK" underscores the power of consistent, incremental progress even for those beginning their retirement journey in their fifties.
Conclusion: The Viability of Late-Stage Saving
While starting over at 51 presents significant challenges, the narrative highlights that strategic debt management combined with a high savings rate can yield substantial results. By leveraging her current income and maintaining the momentum of her recent financial adjustments, Trisha remains in a position to secure her future. Ramsey’s outlook serves as a reminder that retirement planning is not strictly defined by age, but by the rigor and consistency of the financial plan implemented.