‘Starting at rock bottom’: Woman filed for bankruptcy at 24 with $65,000 in debt. How she made it back from the brink
Source Entity
Yahoo Finance
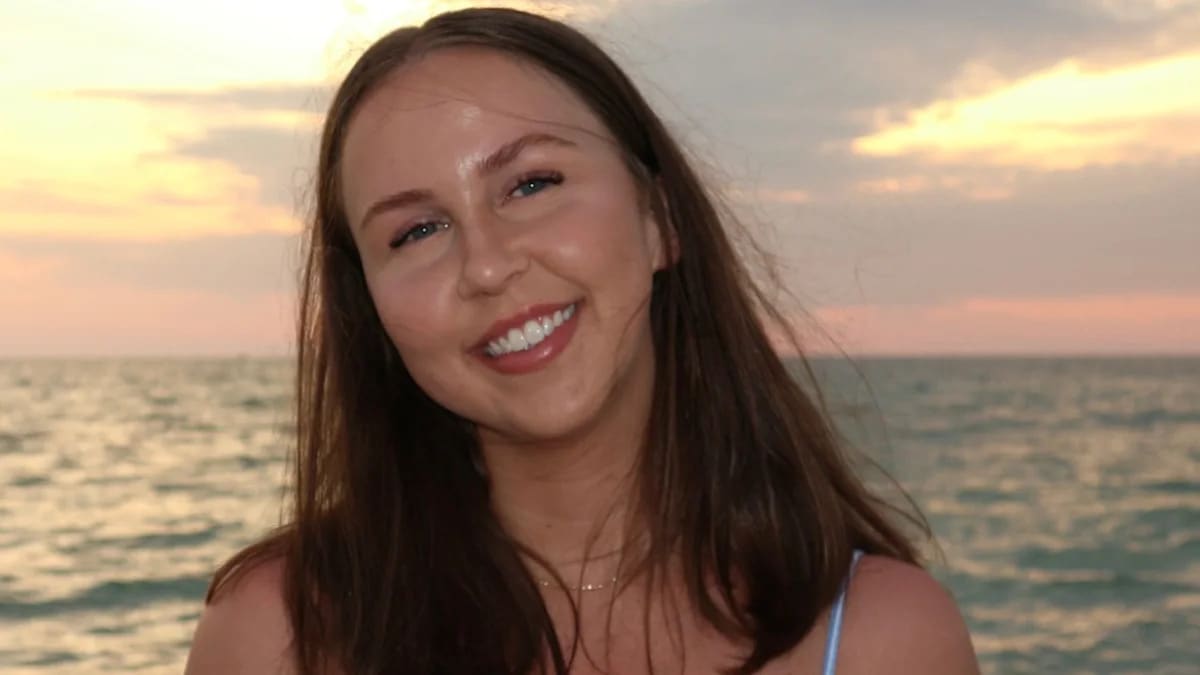
Erin Spencer, who filed for bankruptcy at age 24 due to $65,000 in debt, utilized the legal process to restructure her finances. By managing remaining student and car loans after bankruptcy, she successfully navigated a path toward financial recovery.
The Burden of Early Financial Distress
At the age of 24, a period typically marked by early career exploration and personal growth, Erin Spencer found herself facing a debilitating financial reality. Accumulating $65,000 in debt through a combination of student loans, car financing, and credit liabilities, Spencer reached a point where her monthly obligations far exceeded her income. This situation was exacerbated by personal challenges, including a difficult breakup and the common trap of living beyond one's means, which ultimately led her to a critical turning point.
The Strategic Decision to File for Bankruptcy
Facing the reality of being unable to meet her monthly credit card and line of credit payments, Spencer followed the advice of a trusted colleague to pursue bankruptcy. While bankruptcy is often stigmatized in modern society, it serves as a legal mechanism designed to offer individuals a fresh start when debt becomes unmanageable. For Spencer, the filing provided an immediate, necessary reprieve, allowing her to pause the unsustainable cycle of debt and gain the breathing room required to stabilize her financial life.
Understanding the Scope of Debt Relief
It is important to note that bankruptcy is not a panacea for all financial obligations. In Spencer’s case, the process did not erase her student and car loans. However, the legal restructuring significantly reduced her burden, lowering her payments to a manageable $180 per month for a nine-month period. This distinction highlights the nuanced reality of bankruptcy, where certain debts remain non-dischargeable, necessitating a disciplined, long-term approach to repayment even after a court-ordered reset.
Psychological and Practical Recovery
Spencer described the experience as feeling like she was "starting at rock bottom" rather than simply hitting a reset button. This perspective captures the emotional weight of financial failure, which can be just as taxing as the monetary shortfall. By acknowledging this low point, she was able to shift her mindset toward a more sustainable path, emphasizing that the recovery process is iterative and requires significant behavioral changes in how one manages credit and consumption.
Broader Implications for Young Debtors
Spencer’s narrative serves as a cautionary tale and a lesson in financial resilience for young adults. Her experience underscores the dangers of high-interest credit liabilities and the importance of financial literacy at an early age. As debt levels among young people continue to rise, her story highlights the necessity of seeking professional advice early and understanding the legal tools available to manage insolvency before it spirals out of control.
Conclusion
Erin Spencer’s journey from $65,000 in debt to a position of greater stability illustrates that bankruptcy, while difficult, is not the end of one's financial life. By taking the hard step of restructuring her debt, she gained the necessary leverage to rebuild. Her story serves as a reminder that with the right guidance and a commitment to fiscal discipline, it is possible to navigate back from the brink of total financial collapse.