Nebraska couple lost $59,759 home over $588 tax debt; compensation claim revived
Source Entity
TOI WORLD DESK
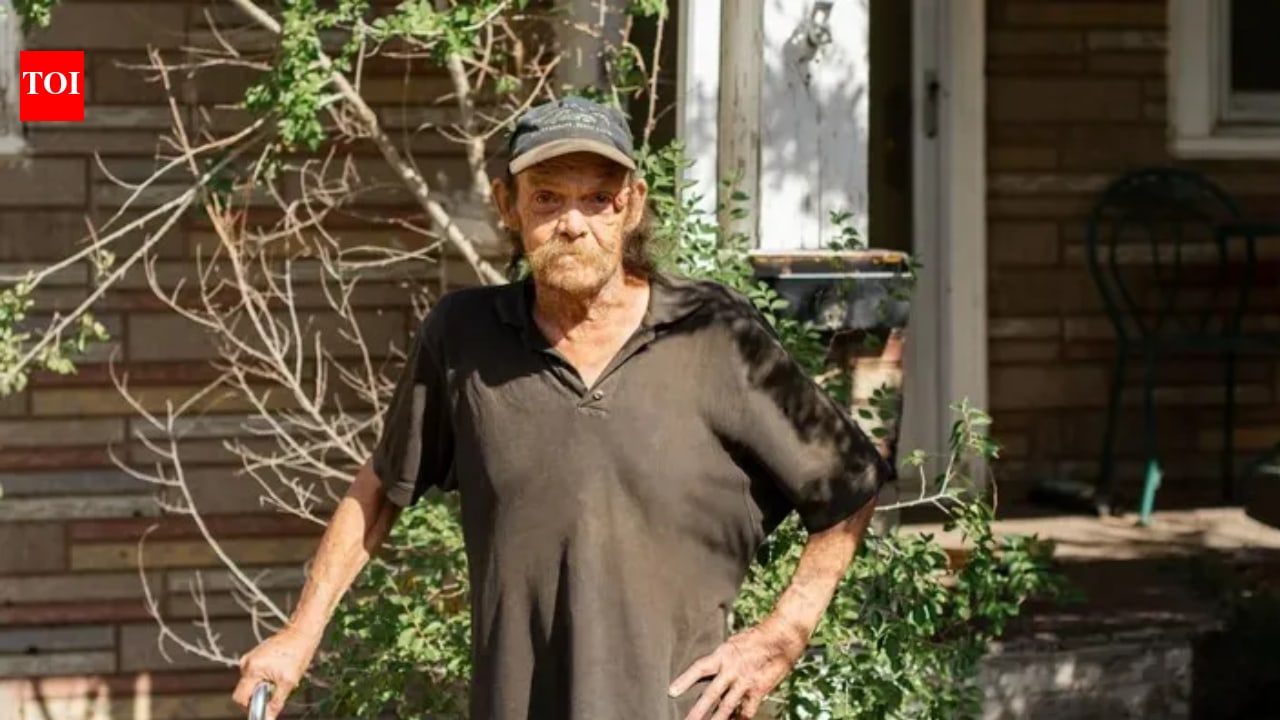
The U.S. Supreme Court has established that surplus funds from tax foreclosure auctions must be returned to homeowners based on the sale price. This ruling addresses constitutional concerns regarding the seizing of property for minor tax debts.
The Constitutional Limits of Tax Foreclosure
The recent intersection of property rights and local tax enforcement has culminated in a series of landmark judicial interventions. Across the United States, homeowners have faced the devastating loss of their properties due to remarkably small tax debts. In Michigan, a family lost a $194,400 home over a $2,241.93 tax obligation, while in Nebraska, Kevin and Terry Fair faced the loss of a $59,759 home for a mere $588.21. These cases have forced the judiciary to address the constitutional boundaries of local government authority when collecting unpaid property taxes.
Defining Just Compensation
The U.S. Supreme Court’s decision in Pung v. Isabella County provides a critical framework for how surplus funds are handled after a tax foreclosure. The Court clarified that "just compensation" under the Fifth Amendment is tethered to the actual proceeds of a public auction rather than the open-market assessed value of the home. By ruling that the surplus from the auction must be returned to the original homeowner, the Court has effectively limited the ability of local governments to profit from the equity of citizens who fall behind on tax payments.
The Nebraska Precedent
Parallel to the Michigan case, the legal battle involving the Fair family in Nebraska highlights the systemic risks homeowners face when tax liens are sold to private entities like Continental Resources. Initially, the couple’s claims were stifled, but the intervention of the US Supreme Court and the subsequent revival of the case by the Nebraska Supreme Court marks a significant shift. This legal trajectory underscores the tension between statutory tax collection methods and constitutional protections against the uncompensated taking of private property.
Shifting the Burden of Equity
Historically, many jurisdictions operated under statutes that allowed the government or private debt purchasers to keep the entirety of a property's value after a tax sale, regardless of the size of the initial debt. This practice effectively allowed for a windfall gain at the expense of the property owner. The current judicial trend suggests a move toward balancing administrative efficiency with the fundamental right of individuals to retain the equity in their homes beyond the amount owed to the state.
Implications for Local Governance
These rulings will necessitate an immediate overhaul of tax foreclosure procedures at the municipal and county levels. Local governments must now ensure that their tax sale processes are transparent and that they facilitate the return of excess funds to the former owners. This change not only protects individual homeowners from predatory debt collection practices but also standardizes the legal expectations for property tax enforcement across the nation.
Future Trends in Property Law
Looking forward, we can expect increased scrutiny on the sale of tax liens to third-party investors. As the legal community aligns with the Supreme Court’s interpretation of the Fifth Amendment, states will likely implement stricter oversight to prevent the "taking" of homes for nominal debts. The focus has shifted from mere revenue collection to the preservation of property rights, signaling a more protective era for American homeowners against aggressive tax enforcement strategies.