Insurer withheld claim for stolen Splendor; consumer court awards Rs 61k to owner
Source Entity
SAURABH THAKUR
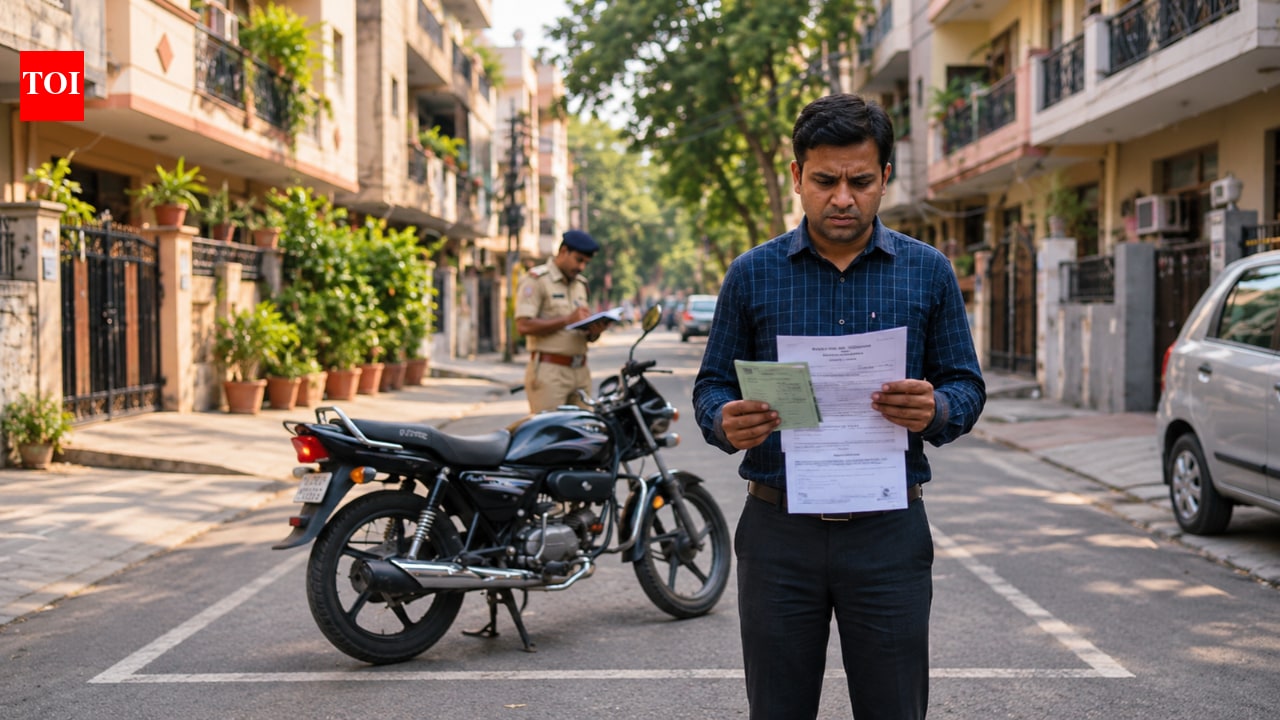
Consumer commissions in Haryana and Telangana have ruled against insurance companies for unfair claim rejections. The rulings mandate payouts for a stolen motorcycle and a fatal road accident, highlighting the growing judicial scrutiny on insurance service deficiencies.
Consumer Commissions Crack Down on Insurance Denials
Recent rulings from consumer commissions in Haryana and Telangana mark a significant shift in how insurance disputes are settled in India. In two distinct cases, insurance providers were penalized for rejecting claims on grounds that were deemed insufficient or contractually invalid. These decisions underscore a growing trend of judicial bodies prioritizing the rights of the policyholder over the often-opaque internal policies of insurance firms.
The Case of the Stolen Hero Splendor
In Haryana, a consumer commission addressed a dispute where an insurer refused to settle a claim for a stolen Hero Splendor. Despite the owner providing necessary documentation and law enforcement confirming the vehicle remained missing, the insurer withheld the claim. The commission ruled this as a clear deficiency in service, ordering the insurer to pay Rs 71,247, which includes the insured value, compensation, and legal expenses. This decision serves as a reminder to insurers that valid documentation and police reports should be sufficient evidence to process theft claims without undue obstruction.
Challenging License-Based Rejections
Simultaneously, a notable case in Telangana involved SBI General Insurance, which had rejected a Rs 20 lakh personal accident claim following the death of a farmer. The insurer cited the absence of a driving license as the reason for denial. However, the family contested this, successfully arguing that the specific insurance policy did not mandate a driving license clause for coverage. The consumer commission facilitated a settlement of Rs 18 lakh, mandating payment within 30 days or face a 9% interest penalty on the outstanding amount.
Broader Implications for the Insurance Sector
These rulings highlight systemic issues within the insurance sector, where companies often rely on technicalities to avoid payouts. By challenging these rejections, consumer courts are forcing insurers to adopt more transparent practices. These precedents suggest that policyholders are gaining more leverage when insurers attempt to circumvent their obligations, particularly when the policy terms explicitly contradict the insurer's denial reasoning.
Strengthening Consumer Protection
These cases emphasize the efficacy of consumer commissions as a check-and-balance mechanism. By awarding compensation and legal costs, these courts are not only providing relief to individuals but also creating a financial deterrent against unfair claim rejection practices. As more policyholders become aware of their rights, the insurance industry will likely face increased pressure to simplify policy language and improve claims processing efficiency.
Future Trends and Conclusion
Looking ahead, it is probable that regulatory bodies will continue to emphasize the 'spirit' of the insurance contract rather than narrow, exclusionary clauses. Future trends indicate that technology-driven claim verification and more rigorous oversight of insurance companies will become the norm. Ultimately, these rulings serve as a vital protection for the common citizen, ensuring that the safety net promised by insurance providers remains functional and reliable in times of distress.