HSA-eligible health plans in 2027: What to know about tax savings vs. higher deductibles
Source Entity
US Top News and Analysis
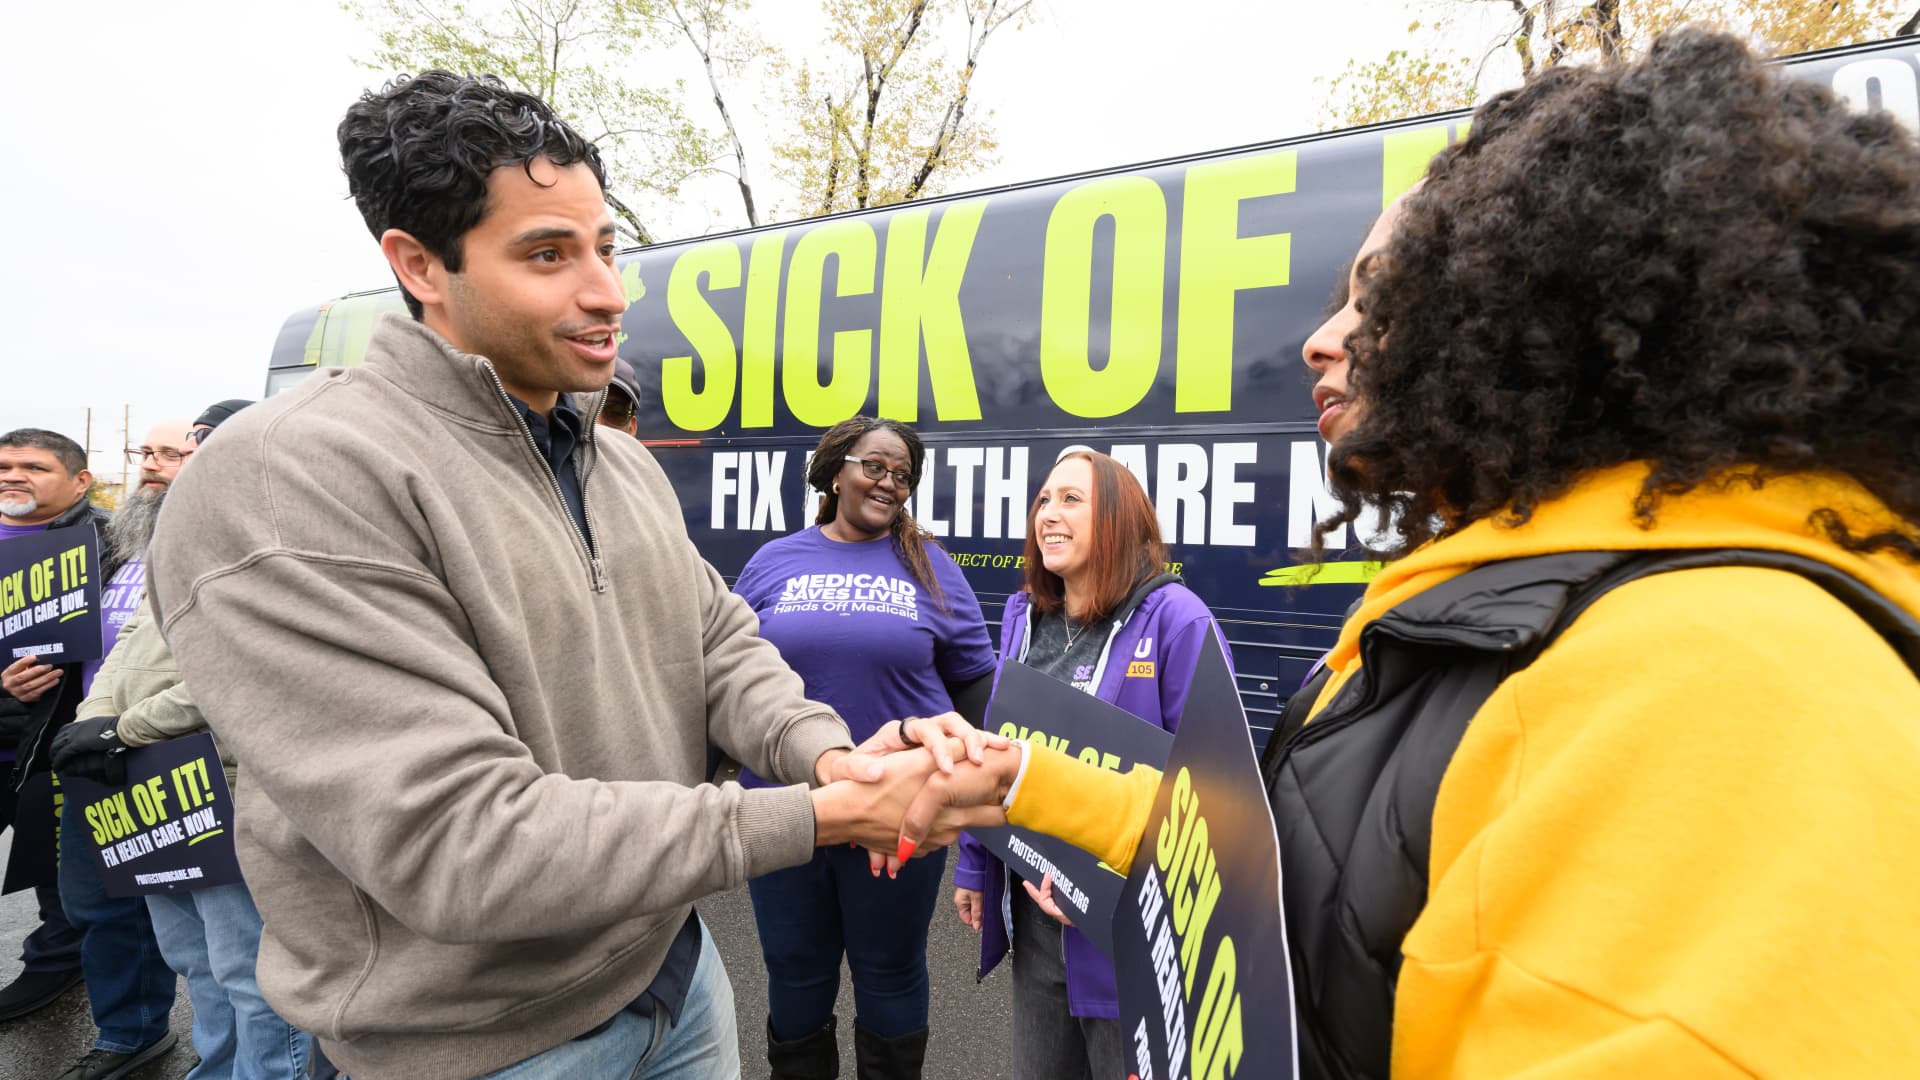
As open enrollment for 2027 begins, employees must weigh the tax benefits of HSA-eligible high-deductible plans against increased out-of-pocket costs. This financial decision occurs amidst broader national debates regarding healthcare affordability and legislative uncertainty.
Navigating Healthcare Choices in 2027: The HSA Dilemma
As the 2027 open enrollment season approaches, millions of employees are once again tasked with the complex decision of selecting a health insurance plan. A primary point of contention for many is the choice between traditional health plans and High-Deductible Health Plans (HDHPs) that qualify for Health Savings Accounts (HSAs). This decision is not merely a logistical one but a significant financial calculation that requires balancing immediate premium costs against long-term tax advantages and potential future medical liabilities.
The Mechanics of the Triple Tax Advantage
The appeal of an HSA-eligible plan is largely driven by its unique 'triple tax advantage.' Contributions made to an HSA are tax-deductible, reducing an individual's taxable income for the year. Furthermore, the funds grow tax-free through investment options, and withdrawals remain tax-free as long as they are utilized for qualified medical expenses. This structure effectively transforms the account into a powerful long-term savings vehicle, provided the individual has the liquidity to cover the higher out-of-pocket deductibles associated with these plans.
The Trade-off: Premiums vs. Out-of-Pocket Risk
While the tax benefits are compelling, the fundamental trade-off of an HDHP is the increased financial burden at the point of care. High-deductible plans generally offer lower monthly premiums, which appeals to healthy individuals or those with predictable, low-frequency medical needs. However, for those with chronic conditions or unexpected health events, the higher deductible can lead to significant out-of-pocket costs before insurance coverage fully kicks in. This necessitates a careful assessment of one's personal health history and financial readiness to manage sudden expenses.
The Broader Context of Healthcare Affordability
The timing of these decisions is particularly poignant as healthcare affordability remains a central theme in national discourse. Recent political events, such as the 'Sick Of It' bus tour in Denver, highlight how healthcare costs have become a cornerstone of the cost-of-living debate. As candidates engage with voters on these issues, the uncertainty regarding potential legislative shifts in the new Congress adds a layer of complexity to how individuals view their insurance options. Voters are increasingly sensitive to the gap between rising healthcare premiums and the actual quality of coverage received.
Future Trends and Legislative Uncertainty
Looking ahead, it remains unclear how a new Congress will address the systemic pain points of healthcare affordability. While HSAs provide a mechanism for individuals to manage costs, they are often viewed as a market-based solution that shifts a greater portion of risk onto the consumer. As policy discussions continue, employees must remain vigilant, understanding that their 2027 enrollment choice is being made in an environment of political flux where the landscape of employer-sponsored insurance could continue to evolve.
Concluding Summary
Ultimately, the choice to enroll in an HSA-eligible plan requires a disciplined approach to financial planning. While the tax advantages are undeniable, they must be weighed against the reality of high deductibles. As political debates continue to center on the cost of care, employees should view their 2027 insurance selection as a critical component of their overall financial health strategy, balancing current needs with the unpredictable nature of future medical expenses.