Three friends on their student debt: one paid off, one chipping away and one creeping up
Source Entity
BBC News
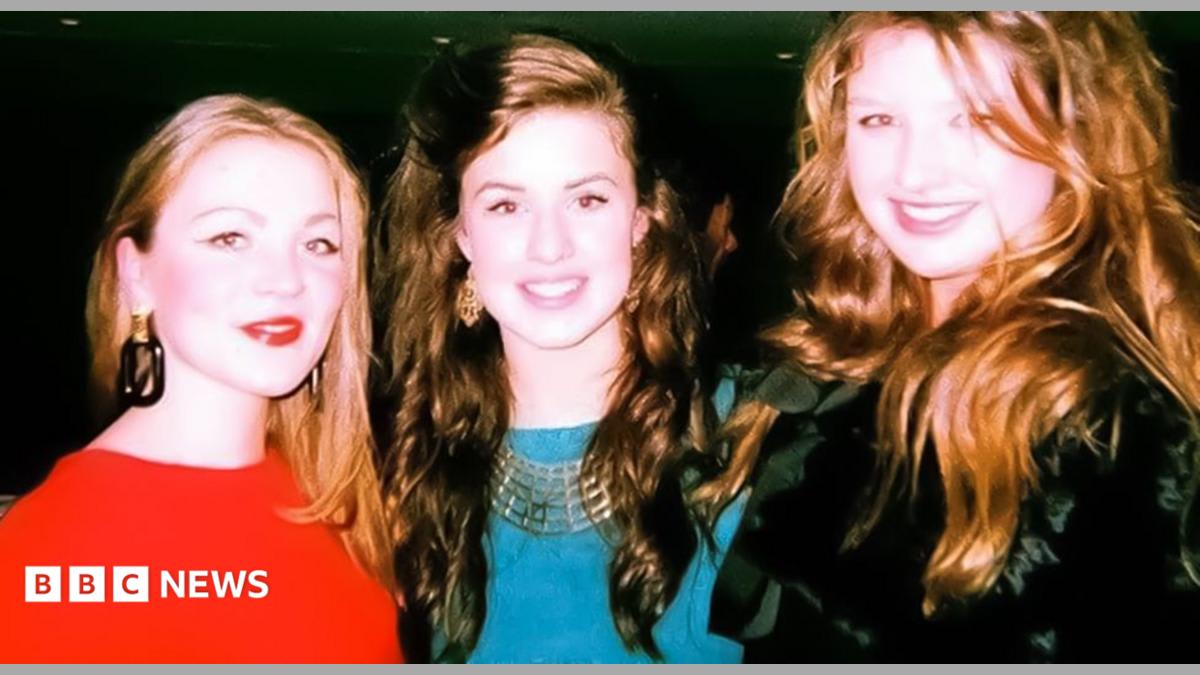
Three friends who started university in 2012 face vastly different financial realities regarding their student debt. Despite starting with identical loans, their divergent career paths and interest rates have led to disparate repayment outcomes.
The Divergent Paths of Student Debt
The story of Lizzy, Charlotte, and Libby serves as a poignant microcosm of the modern student finance landscape in the United Kingdom. Entering the University of Newcastle in 2012, these three friends began their academic journeys at a historical inflection point. This period marked the controversial tripling of tuition fees to £9,000 per year in England and Wales, coinciding with the introduction of the 'Plan 2' loan system. While their initial academic experiences were shared, the subsequent decade has revealed how individual professional trajectories interact with complex debt structures to create starkly different personal financial realities.
The Burden of Plan 2 Loans
At the core of this disparity is the nature of the Plan 2 loan structure, which accrues interest from the very moment the funds are issued. For many students entering higher education during this era, the immediate financial obligation felt abstract, often overshadowed by the pressing demands of sports practice and academic attendance. However, as these individuals have transitioned into their early 30s, the compounding nature of this interest—coupled with the principal amount of approximately £37,500—has moved from a background concern to a central pillar of their financial planning.
Career Trajectories and Financial Reality
As the friends' paths diverged post-graduation, their ability to service these debts became tied to their respective career successes. The narrative highlights a critical tension: while two people may start with the same debt load, the variance in salary growth significantly dictates whether a loan is being paid off, gradually reduced, or, in some cases, growing due to interest outpacing repayments. This phenomenon illustrates how the 'graduate premium' is not distributed evenly, leading to a situation where the debt burden becomes a personal weight based on employment sector and income volatility.
Long-term Implications for Graduates
This decade-long observation period underscores the long-term psychological and economic impact of the 2012 fee reforms. For many in this cohort, the debt is not merely a financial figure but a persistent factor influencing major life decisions, such as housing, savings, and career mobility. The shift from seeing debt as a 'less relevant' topic to a 'forefront' priority reflects the maturation of the millennial graduate who is now contending with the harsh realities of a high-interest repayment scheme.
Future Trends and Systemic Challenges
Looking forward, the experiences of Lizzy, Charlotte, and Libby highlight the systemic challenges facing the UK higher education funding model. As these graduates reach their prime earning years, the sustainability of the Plan 2 model remains a subject of intense debate. The fact that debt levels can 'creep up' despite consistent effort suggests that the current repayment threshold and interest rate mechanisms may not align with the economic realities faced by all graduates, potentially necessitating future policy reforms to address these widening disparities.